
’For brokers and insurers, the traditional business description is changing and evolving all the time – and if we’re not capturing that then it becomes a problem when claim time comes,’ says practice lead, wholesale speciality and delegated authority
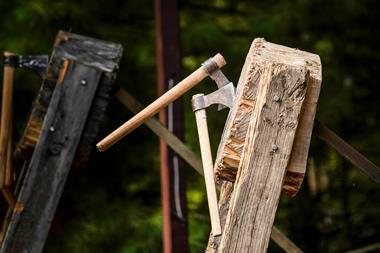
In recent years it has been hard not to notice the increasing occurence of weird and wonderful leisure activities that have become commonplace for consumers – with activities from axe throwing to virtual reality gaming and interactive escape rooms all now available across the country.
According to a recent Hiscox report, entitled New Leisure, New Risks, 75% of surveyed UK leisure providers have added a new activity or plan to add one soon, whether that’s events, food and drink, play areas, tours or venue hire.
But, as venues look to diversify their offerings to attract punters, beat out competition and, ultimately, increase revenues, these businesses may be inadvertently exposing themselves to more risks than they are fully equipped to manage.
As squeezed budgets make consumers more selective, Simon Ratcliff, head of commercial property and casualty at specialist insurer Hiscox, noted that leisure businesses are “having to offer a more diverse range” of attractions that present “good value for money”.
Speaking during a recent Insurance Times webinar entitled New Leisure, New Risks, which was hosted on 10 November 2026 in association with Hiscox, Ratcliff explained that this shift in consumer behaviour has led to a rise in attractions that keep groups “entertained for a whole day” with a demand for participatory activities.
Indeed, the Hiscox report found that 62% of operators said customers want more immersive experiences, 54% want more participatory activities and 47% want more niche or specialist offerings.
For brokers, Jack Westlake, practice lead, wholesale speciality and delegated authority at Specialist Risk Group, believes that this means “more attention” needs to be paid to the evolving risk these diversified activities pose.
As these businesses diversify to compete in the market, Westlake explained that there tends to be a rise in “operators having no experience” and “no loss history in these particular activities”.
This presents a challenge for insurers to place the risk, he said, as it goes beyond precautions the insured has even considered or can afford to account for.
He continued: “Ultimately, for brokers and insurers, the traditional business description is changing and evolving all the time and if we’re not capturing that then it becomes a problem when claim time comes.”
Unfamiliar exposures
From a legal and civil liability perspective, businesses moving beyond their original expertise can create unfamiliar liability exposures for them.
Read: McLarens launches specialist sports and leisure claims service
Read: Hiscox UK grows 11.1% as it builds on ‘strong momentum’
Explore more risk management related content here, or discover more news here
This was the view shared by Richard Rowe, partner at DAC Beachcroft, who noted that leisure companies are bound by civil liability laws that “depend upon establishing a duty of care, breach, causation and actionable loss”.
For Rowe, the “critical question” for a diversified leisure business is whether a risk is inherent to an activity voluntarily undertaken by a visitor, or arises from aspects of the premises, equipment, organisation or operation that the business can reasonably control.
He continued: “That makes risk assessment particularly important as businesses diversify, [and] existing systems of risk assessment, inspection, maintenance, training and supervision should always be reconsidered against what they’re moving into, rather than the historic description of the business.”
Despite greater exposure on their doorstep, the Hiscox report revealed that a third (33%) of surveyed leisure businesses have not checked whether their insurance still reflects those changes in service.
This is especially concerning from an underwriting perspective, Ratcliff noted, as the more participatory nature of these activities has changed the casualty risk substantially.
For example, he described an example of a business where the primary trade was provision of golfing facilities, but also hosted a whole list of activities that carried risk – from whisky tasting to hiring segways.
He continued: “It’s not enough to just trust the principal business description or, as we call it, the primary trade in our underwriting system.
“That won’t tell you necessarily what this business is all about [and those secondary trades] change that casualty risk quite substantially. I tell underwriters [that they have] got to dig deep and interrogate those activities and don’t just trust the initial business description that might be on the system in front of you.”
Clients ‘cutting corners’
The role of the insurance industry in supporting clients with these risks is even more pertinent when considering that some leisure firms are “cutting corners” when performing their own risk assessments, Westlake explained.
He said that he had seen “a number of opportunities come through where clients have used artificial intelligence (AI) to do a risk assessment or a health and safety check”.
These AI assessments are not always entirely accurate or relevant to UK litigation and are no replacement for professional risk advice, he explained.
Similarly, Rowe noted that there is a misconception that waivers can limit a company’s liability for death or personal injury caused by its negligence.
Under section two of the Unfair Contract Terms Act, Rowe explained that a customer signing a waiver accepting the risk of injury does not “make the cases disappear” and can only be used evidentially to show the claimant was aware of the risks undertook.
Ultimately the duty of care remains with the leisure business, Ratcliff said, and it is crucial that the underwriter is certain that a “thorough” and “probing” risk assessment has been carried out to specify what controls the company has in place.
“One thing my claims people always tell me is that it’s one thing for an insured to have exhibited the right behaviours, but it’s another thing to prove that they did,” he continued.
“Sometimes the documentation supporting those protocols is just as important as the protocols themselves.”
A ‘tripartite relationship’
While diversification itself is not inherently problematic for leisure businesses, there is risk that comes alongside evolving faster than the legal, contractual and insurance frameworks can keep pace with.
In turn, Rowe explained that supporting clients to understand how their risk is changing is “critical”.
This could include checking in with businesses at renewal for updates on customer activity, participation, demographics, third-party involvement and additional offerings, he explained.
Ratcliff added that understanding a business’s dependencies is also imperative.
He explained: “Some of these venues can be money-spinning enterprises and I’ve seen some quite chunky business interruptions (BI), long and short, and often with longer indemnity periods because it would take longer to recover in the event of significant damage.”
When assessing BI exposure, he said underwriters need to understand what a business relies on to operate, including key personnel, equipment and seasonal trading periods.
He warned that without assessing these dependencies, underwriters “don’t understand the BI risk”.
This broader understanding of the client should also inform, he explained, how the insurer should be providing “a broad a range of covers as possible for that customer that covers the whole business”.
Westlake added that this means being in the habit of having that “conversation early” to advise the client and form that relationship with them before a potential claim occurs.
He finished: “It’s truly about working with the client to why is this a very good insurable risk?
“Why should we be doing it? How can we bring it to life for the insurer? I’m a big advocate of bringing the insurer in and getting them involved. It’s a tripartite relationship.
Webinar action points
-
Assess risks beyond clients’ primary business descriptions to identify emerging risks from new activities.
-
Ensure risk assessments are thorough and prove into how staff training, maintenance and safety procedures reflect new offerings.
-
Engage clients and insurers early to understand exposures and secure appropriate cover
She joined the title after completing a Master's degree in Journalism in 2025, having previously graduated with a degree in English Literature.View full Profile



No comments yet