
‘We see that professional drivers are going to have very different demands when it comes to loss of earnings and presenting for credit hires,’ says director of claims strategy
The high street has transformed in the last decade, with food delivery and taxi services available at the touch of a button and ready in minutes.
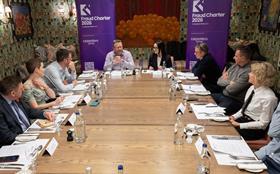
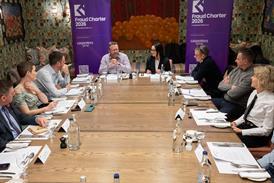
According to law firm Carpenters Group, speaking at the latest Fraud Charter roundtable on 5 November 2026, hosted by Insurance Times at London’s Charlotte Street Hotel, taxi service Uber had forecast around 9% business growth for 2027, while online grocery shopping and delivery firm Ocado had ringfenced 14% growth in its vehicle fleet and overall mobility for next year.
This observed change in the commercial motor landscape has opened Pandora’s box when it comes to new avenues for committing insurance fraud.
Counter fraud experts attending November’s event warned that year-on-year growth in gig economy services and an uptick in associated customer demand could pose new opportunities for fraud in the credit hire market.
Fleur Lewis, head of financial crime and operational oversight at Covéa Insurance, told roundtable delegates that this “increase in innovation in lifestyle is going to be an enabler” for fraud linked to the gig economy because customers ”don’t ever have to leave home because we can bring everything to you [that] you want”.
She said that as consumers increasingly expected goods and services to be brought directly to their homes, “every company that will sell anything online is forced into this [gig economy landscape] to stay competitive”.
Simon Smith, director of claims strategy at Carpenters Group, added that professional drivers operating in the gig economy are, therefore, an “emerging” area for insurers to watch because this marketplace has led to the creation of more sole traders whose livelihoods depend on access to a vehicle.
‘Sting in the tail’
One emerging risk here, Smith warned, derives from alternative vehicle rental arrangements that appear to be “becoming more commonplace”.
Read: Insurers risk ‘automating vulnerabilities’ at scale as fraudsters exploit phone channels
Read: Fraud Charter Ghost Broker Focus – How proactive are insurers in tackling ghost broking?
Explore more fraud related content here or discover more news here
He said this was especially the case in the “Uber car technology space”.
Smith explained that some prospective private hire drivers have been “really struggling” to secure credit for two or three-year personal contract purchase (PCP) deals to obtain vehicles for private hire work.
Therefore, some individuals were turning to companies offering rental vehicles with embedded Uber insurance via a third party “agent”.
However, he explained that buying insurance from third party agents can potentially expose these professional drivers to opportunities for exploitation – for example, by ghost brokers.
Smith noted that this trend feeds into wider “cost of living” and “affordability” pressures as drivers that need to get back on the road for work purposes may increasingly look towards alternative ways of accessing embedded insurance.
He added there is potentially a “sting in the tail” with these types of vehicle rental models that could spread across the wider mobility market.
He continued: “It’s quite common that a vehicle can be on [a] multicover [policy] from a motor insurance database (MID) perspective. I think there’s potentially a loophole in there.”
Expecting challenges
Smith also noted additional credit hire challenges created by professional drivers and sole traders who are shifting to electric vehicles (EVs) to avoid congestion zone charges in the capital.
Kevin Perkins, head of defence at Carpenters Group, explained that EVs often “give fraudsters legitimate excuses to say the vehicle needs to be inspected by some specialist mechanic” due to the added complexities and resources needed for an EV repair.
He told Fraud Charter delegates that when an EV is damaged, it is easy for repair shops “to elongate that credit hire period because of all the hoops you have to jump through to get it back on the road”.
Perkins continued: “You do get particular groups getting vehicles for non-fault accidents into backstreet garages, which will say ’we are waiting for the instruction manual to come over from Shanghai’ and all the rest of it.
“If it goes through your traditional claim, it’s fine because insurers deal with it quickly. But if it’s a backstreet garage, then it becomes really difficult.”
Smith finished: “We see that professional drivers are going to have very different demands when it comes to loss of earnings and presenting for credit hires.
“So, we expect some more challenges.”
She joined the title after completing a Master's degree in Journalism in 2025, having previously graduated with a degree in English Literature.View full Profile





No comments yet