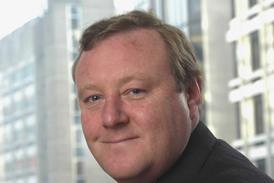
Carla McDonald, director of product management at LexisNexis Risk Solutions, says that claims processes, particularly at FNOL, often still rely on fragmented, reactive models built for a simpler market
UK motor insurance premiums may have stabilised, but the cost and complexity of motor claims continue to rise. Repair bills remain under pressure, operational demands are increasing and the FCA is scrutinising whether customers receive fair value.
One claims data issue still needs more attention – the quality of data available at first notification of loss, or FNOL.
At FNOL, claims handlers make decisions that shape everything that follows – triage, routing, indemnity spend, customer experience and loss ratios. Yet many decisions are still made with incomplete or unverified information.
The result is delay, rework, misrouting and higher costs at every stage of the motor claim.
Two examples show how quickly the impact can build. After a collision, third party contact details often must be found or verified before the claim can move forward, adding friction from the first interaction.
Windscreen claims create a different but equally costly challenge. A stone chip that appears to be a routine repair may involve a windscreen with advanced driver assistance systems, requiring specialist recalibration. Once technology and calibration requirements are factored in, a windscreen repair can cost an insurer up to about £1,000. Across claim volumes, those costs add up quickly.
Better claims data
Pricing and underwriting have become highly data driven, but claims processes, particularly at FNOL, often still rely on fragmented, reactive models built for a simpler market.
The answer is not more manual intervention. It is better claims data, delivered earlier. When claims handlers have richer, more connected intelligence at FNOL, they can validate details instead of chasing them, route claims correctly from the outset, flag suspicious activity before losses escalate and help customers reach a faster resolution.
That requires a different approach across the motor claims ecosystem. The challenge does not sit with insurance providers alone. It also runs through repair networks, claims management companies, credit hire organisations and supply chain partners.
Fragmented data at one point in the chain creates problems elsewhere. A connected view of the claim, available from the moment it is first reported, can help the market move from reactive to proactive decision-making.
The first few minutes of a motor claim should not be the most data-poor point in the insurance lifecycle. As vehicles become more complex, repair costs rise and customer expectations increase, claims intelligence must evolve at the same pace.