
Underwriters do not read every page of renewal documentation in practice, panellists said, highlighting the importance of tracked changes and clear communication over policy wording amendments
Underwriters cannot realistically review every clause in a policy at renewal, otherwise the Lloyd’s marketplace would “grind to a halt”.
That was according to Harry Wright, barrister at 7KBW, who was speaking during the London Market Association’s (LMA) Dispelling the Myths and Misunderstandings of Insurance Law panel on 27 October 2026.
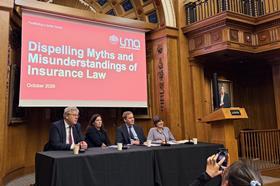
Wright said the practical realities of the London market mean underwriters often rely on mechanisms such as tracked changes to identify differences between policy versions.
And referring to evidence given by underwriters in previous litigation, Wright said: “On a renewal, we do not turn every page and read every clause. Because if we did, Lloyd’s would grind to a halt and no other business would ever be underwritten.”
Amendments
The claim arose during a debate about amendments to standard LMA clauses and whether underwriters can reasonably be expected to identify every change themselves.
Read: Antares Global promotes for newly created chief actuary role
Read: Specialist MGA incubator appoints new chief digital officer
Explore more London market-related content here, or discover other news stories here
Arabella Ramage, legal and regulatory director at the LMA, noted that seemingly minor amendments could have a significant impact on policy wordings.
She said the addition of only a few words could completely alter the meaning of a clause, particularly in relation to exclusions.
And Wright said disputes can become fact-sensitive where changes are not clearly highlighted during the placement or renewal process.
Broker role
In turn, Wright highlighted that brokers would be “very well advised” to draw amendments to underwriters’ attention rather than assume they would be identified during the underwriting process.
“If I were the broker, I would definitely not want to be risking that,” he said.
The panel also discussed whether the availability of red-lined documents affects the position and the extent to which underwriters should be expected to spot amendments in lengthy electronic policy documents.
Throughout the debate, speakers emphasised that disputes involving policy wording changes are highly fact-specific and that there is no single answer that applies in every case.
With a background in local journalism, she has previously worked as a freelance reporter covering community stories and gaining valuable on the ground experience.View full Profile




No comments yet