

Insurers are turning to AI to take on repeatable operational work and free up capacity to write more business, with industry leaders saying the technology could finally deliver the efficiency gains promised by previous technology waves
One in nine broker submissions are being declined or left unquoted because insurer operations cannot keep up, despite there being appetite for the risks. But could the implementation of AI solve this problem and jumpstart the insurance industry?
That was one of the questions raised by carrier feedback from Mea Platform’s new The state of insurance operations report, which was published on September 16.
And, the report added, that lack of insurer operational capacity comes just as 83% of the global insurance market said it would support AI executing repeatable operational work.
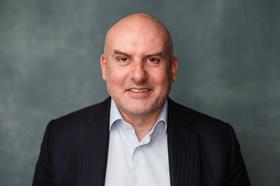
Commenting on the findings, Mea Platform’s chief executive Martin Henley told Insurance Times that the industry’s approach to AI was now becoming more focused on what the technology can actually deliver.
Henley said Mea was founded with a focus on developing technology that worked without common lengthy implementation periods and significant costs, with his scepticism towards the insurtech boom part of the reason the company initially chose to bootstrap.
“I was a bit cynical in my view of the whole insurtech industry, especially the part where people get funding and then burn lots of dollars without actually generating much value,” he said.
And, Henley added, he is now directing this scepticism towards to the cost of AI experimentation, with insurers increasingly considering whether the technology can generate a measurable return.
“You can do a lot of clever things with AI, but it’s also pretty expensive in terms of burning through tokens,” he said.
“What we’re starting to see actually is a bit of a shift towards cost effectiveness and generating ROI.”
Initially focused on data ingestion, Mea has now expanded its focus into wider insurance operations, including underwriting, claims and finance, targeting processes that insurers repeatedly carry out.
Mike McGavick, the former chief executive of XL Catlin who spoke to Insurance Times alongside Henley, said the industry had experienced successive waves of technology that promised to reduce costs, but often added complexity.
“In my time in the industry, we’ve seen wave after wave of technology coming, and we jump all over the newest thing,” he explained.
“The expense ratio never changed. Because we were spending on all the tech, we weren’t getting any real benefit.”
But, McGavick argued that AI could be different, taking on operational work without requiring insurers to build increasingly complex systems around it.
He said: “I believe that today, if you have 15 great underwriters and four great claims handlers, you could handle an almost infinite amount of business, because you could use this AI tech for the rest of the platform.”
This is an alluring thought for insurers, with Mea’s research showing that operational constraints are preventing them from taking on business they would otherwise write.
A capacity problem
The Mea research surveyed senior leaders across underwriting, operations, claims, technology and transformation in North America, Europe and Asia, covering 20 operational activities from submission intake and triage to quote generation, bordereaux processing, claims adjudication and compliance screening.
Read: Insurance Times reveals 2026’s Tech and Innovation Awards winners
Read: Insurance Times launches 2026 AI claims survey in association with RDT
Explore more artificial intelligence-related content here, or discover more news here
Where AI is already running in operations, 61% of respondents reported productivity improvements and 51% reported faster cycle times. Operating costs are expected to fall by 16% over two years.
The research also pointed to a potential competitive benefit from faster operations.
Some 64% of respondents said pricing would most improve how brokers see their business, while 52% cited ease of doing business and 51% AI-driven speed and completeness of submission response.
Henley said the conversations Mea is having with insurers have changed over the last six to nine months, with clients increasingly seeking advice on how to approach AI, rather than simply asking about products.
“Clients and future clients are asking us ’don’t sell us something, come and talk to us about AI strategy and how we should think about this from a leadership level’,” he said.
While insurers have run numerous AI pilots, Henley said production-grade deployments generating significant benefits remained relatively rare.
That leaves insurers facing a question of where to deploy the technology first – and how to move from experimentation to operational use without simply adding another costly technology layer.
Human judgement remains
The research suggested that insurers are drawing a clear distinction between repeatable operational work and decisions that determine how they differentiate themselves.
Some 86% of respondents said consequential decisions should remain with people, not with AI.
Meanwhile, 75% said they would only trust AI for high-consequence underwriting and claims decisions with limited oversight if it used an insurance-specific model or was governed in a hybrid manner.
McGavick said this distinction reflected the importance of human judgement to insurance.
“Your product is the underwriting. People buy that and the claim, which is the ultimate purchase,” he said.
“Everything else, you should leave to the people who understand it.”
While keeping away from these areas, Henley said AI could instead support decisions by bringing together information and surfacing relevant evidence for underwriters and claims professionals.
One broker submission being processed by a Mea client currently contains around 12,000 pieces of information, he said, covering areas such as coverage, locations and equipment.
“The amount of data they can get out of that risk compared to a year ago, when you just couldn’t have humans doing that. It just completely changes the game,” Henley said.
The research found 96% of insurers have AI-led operating model redesign on their agenda, but only 13% currently have an AI-centred operating model. That figure is expected to reach 52% within two years.
Fully AI-native operations, where AI executes defined processes end-to-end while people set policy and manage exceptions, remain below 1% of surveyed respondents.
Henley said the next stage in development for most firms would involve an “agentic operations layer” allowing data to move through insurance processes automatically, with people brought in where human intervention is required.
He said this could ultimately alter the technology stacks insurers have built up over decades.
“We see it’s going to completely change the operating cost base, productivity set up of these companies so substantially that I think people are only just realising that this is the one that will actually make that difference,” he said.
For an industry where operational constraints can already leave wanted risks unquoted, the potential prize for AI is therefore not simply cheaper administration.
It is the capacity to write more of the business insurers already want.
She joined the title after completing a Master's degree in Journalism in 2025, having previously graduated with a degree in English Literature.View full Profile
With a background in local journalism, she has previously worked as a freelance reporter covering community stories and gaining valuable on the ground experience.View full Profile






No comments yet