
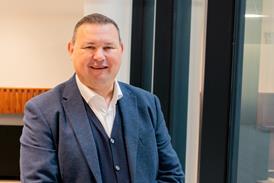

After several years of regulatory scrutiny and a strategic pivot, Wallace explains why Close Brothers Premium Finance is moving from simplification to growth
When Wallace joined Close Brothers Premium Finance (CBPF) in May 2022, he arrived at a business facing decisions about what it wanted to be.
At the time, the operation was larger than it is today but experiencing an uncertain period. Speaking to Insurance Times, Wallace describes his first 18 months at the business as a period of rebuilding and reshaping, during which he and the management team established a clearer strategy for the business.
And, he adds, that work was further complicated because it took place during a time of unprecedented regulatory pressure on the premium finance sector as a whole.
At group level too, uncertainty over motor finance commissions was intensifying. Premium finance, meanwhile, was attracting political and regulatory scrutiny, including former FCA insurance director Matt Brewis’ description of the product as a “tax on the poor”.
“It was a real reflection as to, right, what do we do here?” Wallace tells Insurance Times.
“How do we move the business forward?”
The answer was a strategy centred on three words – simplify, optimise and grow.
At the same time, CBPF was examining the legacy infrastructure associated with its long history in the market and the investment required to modernise it.
However, Wallace felt the division retained a crucial strength in its relationships with brokers.
Those relationships had become particularly important as brokers emerged from the Covid-19 pandemic under pressure to protect income and seek improvements to their commercial arrangements.
“When I joined the business in 2022, we’d seen a lot of people leave to join one of our competitors,” Wallace says.
“So, in 2022 and 2023, there was a bit of ’let’s rebuild, reshape and get a clear strategy in place.’”
The process ultimately led the business to reconsider where it could add the most value and where it should concentrate its capital, expertise and investment.
Simplifying the book
One of the most consequential decisions to follow was Close Brothers’ move away from high-volume personal lines relationships.
Read: Close Brothers Premium Finance announces senior commercial appointments
Read: Does premium finance need fixing?
Explore more broker-related content here, or discover more interviews here
Wallace says the business had adopted a low or no-fee structure for personal lines following the introduction of Consumer Duty. Beyond a default fee and cancellation charge, its approach limited the additional fees imposed on customers and included support for vulnerable policyholders through forbearance and payment holidays.
He believes this was the correct and transparent approach. However, servicing large numbers of relatively small loans involved substantial costs as margins tightened and customers and brokers demanded improved real-time technology.
The business therefore decided to refocus on what Wallace regards as its traditional strength – lending to commercial insurance customers.
However, he stresses that this was not a wholesale exit from personal lines. CBPF continues to fund personal lines business placed through commercial brokers, alongside wheels-based commercial risks involving couriers, fleets and larger transportation businesses.
The relationships it exited were predominantly high-volume aggregator-style accounts involving personal lines loans of around £300 to £400.
The transition was managed through an orderly run-off. Smaller relationships were given around six months to move, while more complex businesses involving technology integrations received approximately 12 months.
“We’re through that exit now and everybody has found a new home,” Wallace says.
The strategy was subsequently given important regulatory context by the FCA’s premium finance market study.
Published in February 2026, the regulator’s final report recognised that premium finance enables customers to spread insurance costs and can help those unable to pay annually access cover.
It found that the product was used for around 48% of motor and home policies in 2023, representing approximately 23 million policies. The FCA decided against a market-wide annual percentage rate cap, mandatory 0% finance or a commission ban, although it retained its focus on individual firms where fair-value concerns remained.
“Thankfully, the FCA recognising that premium finance makes the insurance market available to everybody that needs it,” Wallace says.
“People can’t afford to pay £500 or £600 out of their bank account in one go, so we’re there to help.”
Clarity and investment
Throughout the conversation, Wallace repeatedly emphasised that the outcome of these regulatory developments had provided clarity to CBPF and provided sure footing for its next stage of development.
The premium finance study reinforced the importance of the premium finance product while setting out where the FCA expected improvements. Developments in motor finance, meanwhile, gave the wider Close Brothers group a clearer basis on which to model its potential exposure and plan ahead.
The FCA introduced an industry-wide motor finance redress scheme in March 2026 for customers it concluded had been treated unfairly between 2007 and 2024. It estimated firms would pay around £7.5bn in redress, although parts of the scheme were subsequently suspended following legal challenges.
Wallace does not present the motor finance issue as entirely resolved. However, he says greater certainty over its shape helped “clear the waters” for the group.
“That allowed us to plan better and it gave us that certainty to really kick on with those plans,” he explains.
For the premium finance division, this has included a multi-year technology investment programme spanning its core platform, customer onboarding, affordability checks, collections and recoveries.
Wallace says a real-time point-of-sale affordability check has already been introduced, providing an instant decision on whether customers can afford the finance offered.
Yet some of the most important investment is taking place in less visible parts of the operation.
“The bit that’s not really the sexy and exciting side of things is we’re doing a lot on the collections and recovery side,” he says.
Wallace argues that the costs of providing premium finance extend beyond supplying capital. Firms must identify vulnerable customers, provide breathing space following income shocks and support those who may struggle to understand documentation.
He explains: “We often talk about the front end and the APRs, but it’s often that support we give customers that goes below the radar more than anything else.”
‘A real cash-flow tool’
Having simplified and optimised the business following some challenging years, Wallace says the focus for CBPF is now shifting decisively towards growth.
This strategy has two principal elements – helping existing commercial broker partners increase premium finance penetration and attracting new brokers to the platform.
In commercial insurance, Wallace wants premium finance to be viewed not simply as something required when a customer cannot afford its annual premium, but as a cash-flow tool.
“Brokers should ask their clients whether they want to spend £1m in one payment, or can they spread it out, for a small cost, over 10 or 11 months?” he asks.
The capital retained by using finance, he suggests, could instead be invested in machinery, recruitment or other areas of the customer’s business.
That argument has particular relevance in the current soft market. Falling premiums may benefit customers, but they can also put pressure on broker income. Wallace believes increasing commercial premium finance penetration offers brokers an additional lever to support revenue while giving clients greater control over cash flow – and the scale of this opportunity can be substantial.
Wallace reveals that Close Brothers recently wrote the largest loan in its premium finance division’s history, worth more than £20m.
The loan, he says, demonstrates the contrast underpinning the strategic pivot away from personal lines. The division has moved away from financing large volumes of relatively small personal lines policies while increasing its focus on complex commercial opportunities supported by Close Brothers’ balance sheet and underwriting capability.
Its future growth will still depend heavily on brokers, however.
“Without the brokers, we don’t get access to those markets,” Wallace says.
He believes the firm can differentiate itself through longstanding relationships, specialist knowledge, service and consistency. A new Built for Brokers campaign is intended to reinforce that proposition, while software house integrations and application programming interfaces should reduce friction in digital trading journeys.
After a period defined by restructuring, investment and regulatory scrutiny, Wallace believes the business is emerging in a stronger position.
“We’ve handled a lot in the last 18 to 24 months, but we’ve come out of it in a good spot,” he says.
“The sun, the moon and the stars are starting to align for that real period of growth moving forward.”
With a particular interest in regulation, technology, innovation and political stories, he has covered issues from the multioccupancy buildings scandal to the insurance implications of quantum computing and the growth of new markets.View full Profile





No comments yet