


Insurance Times’ latest webinar with Zurich explored how insurers can use technology to deliver faster, more efficient trading without sacrificing underwriting judgement, broker relationships or the human element of claims
Faster trading and AI-powered tools may be reshaping how insurers trade with brokers, but access to experienced underwriters and claims professionals remains essential, especially when risks become more complex.
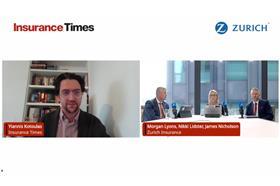
That was a central theme of the recent Efficient Where It Matters, Personal Where It Counts webinar, hosted by Insurance Times in association with Zurich.
The session was chaired by Insurance Times editor Yiannis Kotoulas, who was joined by Zurich’s head of SME trading Nikki Lidster, head of retail commercial Morgan Lyons and chief claims officer James Nicholson.
The discussion drew on Insurance Times’ eTrade research, in which Zurich secured two five-star accolades for 2026 and retained the top spot for insurer eTrading via platforms for a fourth consecutive year, alongside Zurich’s own research into broker expectations.
Speed needs certainty
Speed is important for brokers in the competitive marketplace, but faster trading is only valuable if they can trust the decisions they receive.
Read: Zurich takes ownership of Beazley as court signs off deal
Read: Zurich UK calls for regular property inspections as suspected cannabis farm incidents rise
Explore more insurer-related content here, or discover other interviews here
Lidster said that Zurich was focused on removing the traditional trade-off between speed and certainty by combining underwriting expertise with responsive referral handling.
“Speed absolutely matters, but only if it’s accompanied by certainty,” she said.
She noted that the insurer answers 60% of its phone calls and live chats within 30 seconds, while 51% of submit-to-underwriter referrals are handled within 30 minutes.
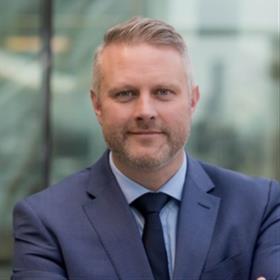
Lidster said Zurich’s SME operation has around 200 underwriters covering 12 SME trade products, making consistency a critical part of the trading proposition.
To support this, the insurer has introduced an AI underwriting assistant that helps underwriters access information more quickly. Although the tool has only been in place for a matter of weeks, early internal results indicate that internal upward referrals have fallen by a third.
Lyons added that consistency in trading was one of the strongest themes to emerge from Zurich’s own research into broker expectations.
He described clear appetite, consistency, access to expertise, flexibility and being contactable as “hygiene factors” insurers need to deliver to earn a place in the market.
That becomes particularly important as insurers seek to expand digital trading into more complex business lines.
Lyons said there remained a “grey space” between risks that can be traded digitally and those that brokers immediately assume require traditional underwriting engagement.
Commercial combined business is one example, with brokers potentially hesitant to place higher-value or more complex risks through a digital environment.
Zurich believes its digital capability extends further than some brokers may assume, but Lyons said confidence would need to be built through engagement with underwriting teams.
“There’s potentially a lack of confidence from our brokers when they get to a certain complexity of risk,” he said.
“All I would say on that is, try us, talk to us, challenge us.”
AI without the robots
That balance between efficiency and expertise also shaped the discussion around AI’s place in the trading relationship.
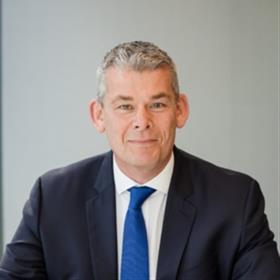
Zurich’s use of AI is currently focused on supporting employees, rather than replacing interactions between brokers and underwriters.
Lyons said the underwriting assistant was designed to learn from Zurich’s “corporate memory”, including questions frequently raised by brokers.
But he was clear that the technology was not intended to become a new interface between Zurich and its broker partners.
“This is not a broker-facing tool. This is very much an internal tool that our teams have access to.”
“We’re not in a place where we want our brokers to be speaking to automated bots. It’s about reducing internal referral times, speeding up response to brokers – it’s not about robots.”
Lidster similarly argued that technology should remove friction, rather than supplant human judgement.
The same philosophy is shaping the insurer’s approach to claims.
Zurich has developed an in-house liability assessment tool tested in motor, Zenesis, which reviews evidence, the circumstances of a claim, case law and other factors before providing an evidence-backed liability assessment.
But the final decision remains with the claims professional.
AI can process information, identify patterns and reduce administrative burden. But complex risks, vulnerable customers and difficult claims still require judgement, empathy and experience.
Relationships still matter
The growth of digital trading could suggest broker-insurer relationships will become less important as more business moves online.
But, during the webinar, panellists emphasised that the opposite was true. They argued that human interaction becomes increasingly important when a risk falls outside a standard digital journey.
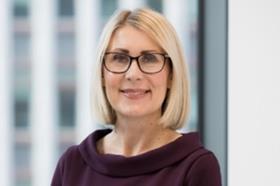
Lidster said brokers trading digitally would still speak to an underwriter when a risk was referred, rather than being pushed towards an automated system.
The insurer only refers around 14% of the quotes it processes through its eTrading platforms, meaning the majority can flow through without intervention.
However, when referrals do occur, the quality and accessibility of the underwriting relationship becomes crucial.
This is particularly relevant as brokers look to trade increasingly complex commercial risks digitally.
Lyons said that he’s still a believer in picking up the phone, adding “it’s about the upfront engagement before that submission’s actually reached us.”
He argued that an early conversation can save time by helping both underwriter and broker establish what matters most before the submission process becomes drawn out.
As routine risks become increasingly automated, the value of strong broker-insurer relationships may actually increase at the point where expertise is needed most.
Feedback is also central to that relationship. Lidster said 53,000 brokers had provided feedback to Zurich’s SME underwriting and claims teams so far this year, with the insurer using that information to make changes to products, platforms and appetite.
She said Zurich had delivered changes to its platforms, rating and appetite in 94% of the weeks so far this year.
For Lyons, the commercial impact of listening to brokers was demonstrated by Zurich’s network trading branch, which was established following feedback from network brokers.
The insurer has subsequently written around 65% more new business with that broker population over the past 12 months compared with the previous year. The implication is that relationship-building is not simply a service metric. Understanding broker needs, acting on feedback and making expertise accessible can directly influence trading outcomes.
Claims as a differentiator
The final stage of the insurance journey may ultimately be where insurers have the greatest opportunity to stand apart.
Nicholson described claims as “the moment where the insurance promise becomes real”.
For brokers, that means knowing an insurer will respond quickly, take ownership and help make a difficult situation easier for customers.
Zurich’s claims operation has around 650 professionals in the UK and manages around £1.3bn of claims. Nicholson said its average response time was under a minute, while its major loss response is within 24 hours.
But speed is only one element of the claims proposition. Nicholson said broker feedback consistently focused on the need to communicate clearly, be pragmatic, provide access to the right people and avoid making brokers chase for updates.
The insurer also has claims wellbeing specialists across its UK teams, who have supported more than 1,000 customers so far this year and delivered 1,700 confidential coaching and counselling sessions.
For Nicholson, that support becomes particularly important when customers are vulnerable or dealing with major losses. The role of technology is therefore not to eliminate the human element, but to support it.
Zurich’s panellists argued that the insurance sector’s approach to claims should mirror the wider message of the webinar – automate what can be automated, while preserving human judgement where it matters most.
That could become increasingly important in a soft market, where insurers have less scope to differentiate themselves through price alone.
Asked whether claims could become a commercial advantage for insurers, Nicholson was unequivocal.
“In a soft market, I genuinely think it is the biggest differentiator,” he said.
The challenge for insurers, he added, is to ensure that where price is “absolutely king”, claims service is not compromised.
The webinar’s central message was clear – technology should make insurance easier to trade, but not at the expense of expertise, judgement and relationships.
As Nicholson put it: “Technology and digital is for the predictable and humans are for the personal.”
Webinar action points
- Use technology to remove friction, not judgement, automating predictable tasks while retaining access to underwriting expertise where decisions require experience, judgement or a more nuanced understanding of the risk.
- Maintain clear routes to human expertise so brokers can quickly access an underwriter with authority when a quote falls outside automated trading or requires additional discussion.
- Measure and act on broker feedback by using regular feedback from brokers to identify friction points across digital trading, underwriting and claims, and turning those findings into tangible changes.
With a background in local journalism, she has previously worked as a freelance reporter covering community stories and gaining valuable on the ground experience.View full Profile





No comments yet