
’I really see a challenge of having them becoming big in Europe at the moment because of restrictions on data sharing,’ says head of partnerships
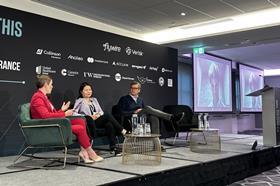
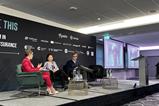
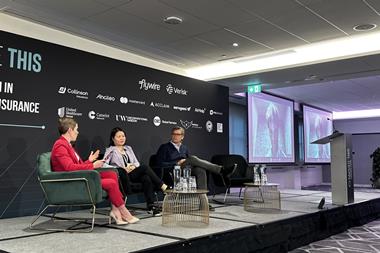
Super applications could create new distribution opportunities for insurers in Europe, but data sharing restrictions may prevent the region from replicating the model’s success in Asia, delegates at the Innovate This conference were told.
Super applications combine multiple everyday services, including payments, shopping, travel and insurance within a single platform, allowing users to access services without switching between applications.
According to Jonas Von Oldenskiöld, head of partnerships at Qover, the model has already become firmly established across Asia. However, he questioned whether it could achieve similar scale in Europe.
“I really see a challenge of having them becoming big in Europe at the moment because of restrictions on data sharing and other things,” he said.
Koot Chiew Ling, group strategy officer at Tune Protect Group, said adoption accelerated across Asia during the pandemic as consumers moved away from cash transactions.
She highlighted platforms including WeChat, Alipay, Touch ’n Go, Shopee and AirAsia Move, which integrate services ranging from payments and e-commerce to travel bookings.
Touch ’n Go, an e-wallet provider that Tune Protect works with, has around 8.5 million users, she said.
“[These applications] are able to tell you what type of interest the customer has, what type of affordability the customer has and at every journey that the customer goes through,” Chiew Ling continued.
Customer data
For insurers, the key attraction lies in the customer data these ecosystems can generate. By analysing transaction histories, spending habits and customer preferences, platforms can identify opportunities to offer more targeted insurance products.
Read: ManyPets eyes launching ‘differentiated product set’ for price comparison websites
Read: Insurtech revolution enters a ‘second coming’ as investment shifts
Explore more insurtech-related stories here, or discover more news here
The approach also allows insurers to access customers through e-wallets, e-commerce platforms and travel businesses that they may struggle to reach through traditional distribution channels.
“I think this is something that’s part of the new generation distribution,” Chiew Ling said, who added that super applications enable insurance to be offered at the point of purchase, rather than relying on customers actively seeking cover.
Despite the potential, Von Oldenskiöld argued that Europe’s attitude towards data sharing remains a significant obstacle.
A self-described “big” fan of super applications, he said the concept’s success ultimately depends on consumers’ willingness to share personal information.
“I think the hindrance, and I’m sure we can cover the challenges, is overall, how really are we a society of sharing data?” he said.
Chiew Ling said she expects adoption would emerge in “different pockets or specialised areas” rather than through broad platforms offering a wide range of services under a single brand.
With a background in local journalism, she has previously worked as a freelance reporter covering community stories and gaining valuable on the ground experience.View full Profile





No comments yet